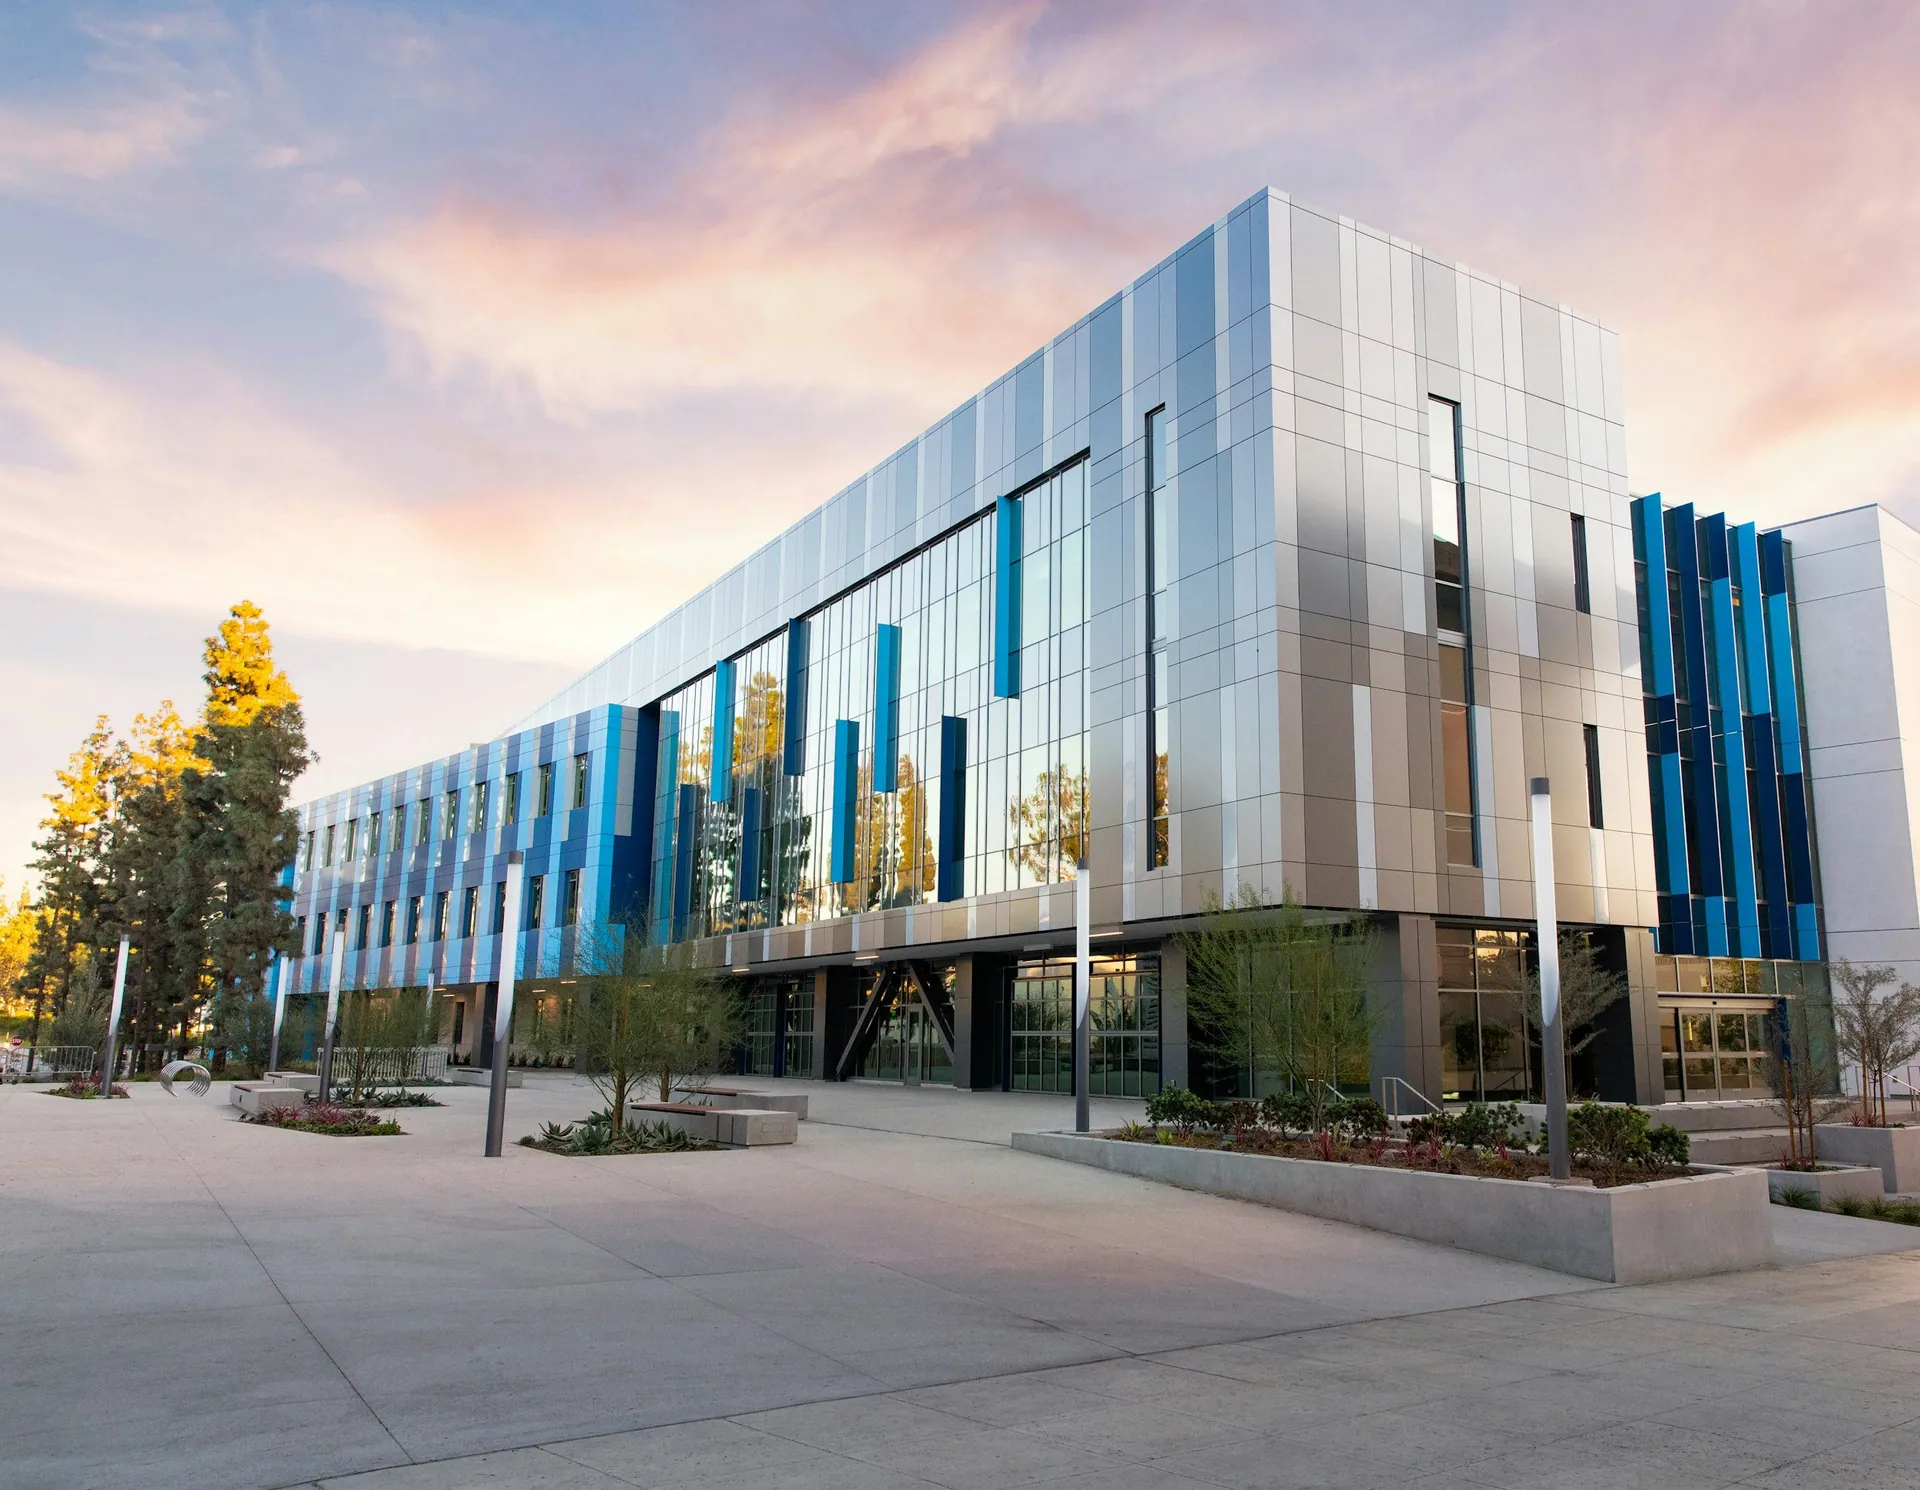
$3.35M Reclassified on a Shopping Center in New Jersey
This New Jersey shopping center was placed in service in October 2025 and studied for the 2025 tax year. It sold for $11.45M, with $3.44M allocated to land, leaving a depreciable basis of about $8.02M.
- Purchase price
- $11.45M
- Depreciable basis
- $8.02M
- Reclassified
- $3.35M
- Share of basis
- 42%
The property and the result
As nonresidential property, the building would otherwise be depreciated over 39 years. After an on-site inspection by USTAGI, the study moved $1.64M into 5-year property and $1.70M into 15-year property, a total of $3.35M or 42% of the basis.
The 15-year share is unusually large. Shopping centers carry big parking fields, paving, site lighting, pylon signs and drainage, all land improvements with a 15-year recovery period. The result is well above the 27.7% median across 170 commercial studies USTAGI has completed.
How the purchase price was allocated
| Category | Amount | Share of price |
|---|---|---|
| Land (not depreciable) | $3.44M | 30% |
| 5-year property | $1.64M | 14% |
| 15-year property | $1.7M | 15% |
| Remaining 39-year building basis | $4.67M | 41% |
How it compares: this study reclassified 42% of the depreciable basis. Across 170 commercial studies USTAGI has completed, the median is 27.7%.
How the study was done
- Study type
- Detailed engineering study
- Inspection
- USTAGI on-site inspection with interior photos
- Cost data
- RSMeans construction cost data
- Timing
- Same-year study for the 2025 tax year
- Placed in service
- October 2025
- Depreciation before the study
- 39-year nonresidential
- Client
- New USTAGI client
What typically qualifies on a property like this
The study assigns each component of the building and site to its IRS recovery period. On a shopping center, these are the kinds of items that usually move off the 39-year schedule.
5-year property
- Tenant finishes and removable flooring
- Decorative lighting and millwork
- Interior signage and displays
- Dedicated electrical and plumbing for tenant equipment
- Security and data systems
15-year property
- Parking fields, paving and curbs
- Pylon and monument signs
- Site and parking lot lighting
- Landscaping and stormwater drainage
- Sidewalks and exterior walkways
What this means at tax time
Property placed in service in 2025 may qualify for 100% bonus depreciation if it was acquired after January 19, 2025, subject to applicable requirements. Where it applies, the $3.35M of reclassified property can be deducted in the first year instead of over 5 and 15 years.
Even without bonus depreciation, 5- and 15-year property is depreciated far faster than the 39-year building schedule, so more of the deduction lands in the early years of ownership. The remaining $4.67M of basis stays on the 39-year schedule.
Studying the property in the year it is placed in service means the faster schedules start on the first return, with no catch-up filing needed.
Questions about this case study
Parking lots, curbs, sidewalks, site lighting, pylon signs, landscaping and stormwater drainage are land improvements with a 15-year recovery period. Shopping centers have a lot of them relative to the building itself.
Yes. Without a study, the building portion of a shopping center is nonresidential real property depreciated over 39 years. A study identifies the components that qualify for 5-, 7- or 15-year recovery instead.
The inspection documents tenant finishes, lighting, signage, dedicated electrical and plumbing, and the site work around the building, with photographs. That record is what supports each classification in the report.
Yes. Improvements made by the owner are part of the depreciable basis, and the study assigns each component to its recovery period in the same way as the original building.
Could your property see results like these?
Tell us about the property and we will estimate the benefit before you commit to anything.
Explore Your Property’s Tax Savings PotentialMore case studies
Results shown are from a completed USTAGI cost segregation study and are not a guarantee of future results. The client is not named, the location is shown by state and amounts are rounded. “Reclassified” is the depreciable basis the study moved into 5, 7 and 15-year property; it is not a tax-savings figure. Outcomes depend on each property and each owner’s tax situation. Consult your tax advisor about your situation.